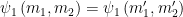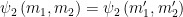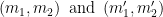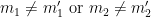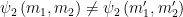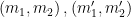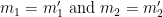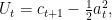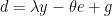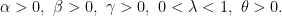Categories
Exam Questions Harvard Macroeconomics Microeconomics Theory

Harvard. Graduate General Exams in Micro- and Macro-Theory. Fall 1993

The following general examination for macroeconomic theory (Spring 1993) has been transcribed from a collection of general exams at Harvard from the 1990s provided to Economics in the Rear-view Mirror by Abigail Waggoner Wozniak (Harvard economics Ph.D., 2005). Abigail Wozniak was an associate professor of economics at Notre Dame before being appointed a senior research economist and the first director of the Federal Reserve Bank of Minneapolis’ Opportunity & Inclusive Growth Institute. She is currently Vice-President of the Federal Reserve Bank of Minneapolis.

Economics in the Rear-view Mirror is most grateful for her generosity in sharing this valuable material.

Because the “Wozniak collection” is over 90 pages long, it will take time for all the exams to get transcribed. To date the following general examinations have been transcribed and posted:

Spring 1991
Microeconomics; Macroeconomics

Spring 1992
Micro- and Macroeconomics

Fall 1992
Micro- and Macroeconomics

Spring 1993
Microeconomics; Macroeconomics

_________________________

HARVARD UNIVERSITY
DEPARTMENT OF ECONOMICS

GENERAL EXAMINATION
IN MICROECONOMIC THEORY
FALL 1993

Instructions:

You have FOUR hours.

Answer a total of FOUR questions, subject to the following constraints:

You must answer questions 1, 2, and 3. You must answer either question 4 or 5 (but not both).

Please use a separate blue book for each question.

Please put only your exam number on the blue book.

Good luck!

1. Indirect Utility (20 points)

This is a question on the indifference map of indirect utility functions.

There are two commodities. The utility function is U(x_1, x_2). Wealth is normalized to w=1, so that the indirect utility function has the form V(p_1, p_2).

Assume that U(x_1, x_2) is continuous and increasing in both arguments.

a) Draw an indifference map of the indirect utility function. Be sure that the axes are properly labelled, that the indifference curves have the proper shape and that the direction of increasing preference is clearly marked. (5 points)

b) Argue that if the utility function U(x_1, x_2) is not quasi-concave then some indirect indifference curve will exhibit a kink. (5 points)

c) Suppose that an indifference curve of the indirect utility function has a piece that is a straight line. What does this correspond to in the direct utility function? Why? (5 points)

d) Consider the slope of an indifference curve of the indirect utility function. Interpret it in terms of the demand function. Justify your answer. (5 points)

2. (20 points)

Consider an industry in which there are two firms: an incumbent and a potential entrant. In each of two periods, total inverse demand in the industry is given by

p = 5 - Q,

where Q is total output. The incumbent’s marginal cost of production c_I can either be “high” (c_I = 2) or “low” (c_I = 1). The incumbent knows the value of c_I, but the potential entrant knows only that the two values each have a 50% probability ex ante. In the first period, the incumbent chooses an output level q_{I1}. The entrant can observe q_{I1} (but not the incumbent’s profit). In the second period the two firms choose quantities q_{I2} and q_{E2} simultaneously. The entrant’s marginal cost c_E is 2. In addition, if the entrant chooses q_{E2} > 0, it incurs an “entry” cost of \frac{1}{2}. The two firms each maximize their (expected) profits (the incumbent maximizes the expected sum of its first- and second-period profits). The model and all its parameters are common knowledge (the value of c_I is not common knowledge, but the fifty-fifty prior distribution on 1 and 2 is common knowledge).

A. Suppose that the entrant concludes, after observing q_{I1}, that the incumbent’s costs are low (i.e., the entrant attaches posterior probability 1 to c_I = 1). Show that, in this case, the entrant will not enter. That is, show that q_{E2} = 0 in the unique continuation equilibrium starting in period 2. What are the incumbent’s second-period output and profit in this continuation equilibrium?

B. Suppose that the entrant concludes, after observing q_{I1}, that the incumbent’s costs are high (c_I = 2). Show that, in this case, the entrant will enter, i.e., choose q_{E2} > 0, in equilibrium. Find the second-period continuation equilibrium outputs and profits for both firms.

C. Using the results from parts (A) and (B), show that there exists a “separating” perfect Bayesian equilibrium for the two-period model in which (i) the incumbent chooses a “small” value of q_{I1} if c_I = 2 and a “big” value if c_I = 1, and (ii) the entrant enters if and only if q_{I1} was small. In particular, show that q_{I1} is at the high-cost monopoly level if c_I = 2 but strictly above the low-cost monopoly level if c_I = 1.

3. Gross Substitute Excess Demand (20 points)

Consider an excess demand system (f_1(p_1,\ldots,p_{L-1}),\ldots,f_{L-1}(p_1,\ldots,p_{L-1})). There is an Lth commodity for which price is 1 and for which demand is not explicitly recorded.

a) How would you determine the demand for the Lth commodity? (5 points)

b) Suppose that the excess demand system for all L commodities satisfies the gross substitute property (when the price of a single commodity goes up the excess demand of each of the other commodities increases). Argue that the competitive equilibrium is then unique. (5 points)

c) Suppose that the excess demand functions for all L commodities are differentiable and that as in (b) the gross substitute property holds. What is the sign pattern induced in the Jacobian matrix of price effects? (5 points)

d) Suppose that the excess demand functions for all L commodities are differentiable and satisfy the gross substitute property. Suppose now that there is a shock (if this is helpful you can limit yourself to a small shock) the effect of which is to decrease the demand for commodities 1 to L−1 at every vector of prices. What should be the effect of this shock on the equilibrium prices of commodities 1 to L−1? Give a justification of your answer which is as rigorous as possible. (5 points)

Part IV:
Answer ONE of the following two questions:

4. Suppose there is another energy shock and the world-market price of oil goes from its present price of under $20 per barrel to $100. Analyze the short and long term effects on growth and distribution from neoclassical, Marxian, and Keynesian perspectives on the simplifying assumption that all energy is imported at the world-market price.

5. Milton Friedman has argued (“The Methodology of Positive Economics”) that a theory should be judged not on the realism of its assumptions, but on its predictive power. What are the principal criticisms of Friedman’s view? How might Friedman respond to the criticisms?

_________________________

HARVARD UNIVERSITY
DEPARTMENT OF ECONOMICS

GENERAL EXAMINATION
IN MACROECONOMIC THEORY
FALL 1993

Instructions:

You have FOUR hours.

You will answer a total of SIX questions from four sections of the exam:

In section I, you must answer the one question given.
In section II, answer both questions.
In section III, answer one of the two questions.
In section IV, answer two of the three questions.

Please use a separate blue book for each question.

Please put only your exam number on the blue book.

Good luck!

PART I:

1. Suppose that each household-producer has the production function,

Y_i = AK_i \cdot (G/Y)^{\alpha},

where A>0, 0<\alpha<1. Y_i and K_i are the ith producer’s output and capital stock, respectively, G is the total of government purchases and public services, and Y is aggregate output. The output of all producers is identical and can be used on a one-for-one basis for consumption, investment, or government services. Each household seeks to maximize utility, given by the standard Ramsey expression,

\displaystyle U = \int_0^{\infty} \left(\frac{c^{1-\theta}-1}{1-\theta}\right) e^{-\rho t}\,dt,

where \theta>0, \rho>0, and c is consumption per person. The economy is closed, depreciation and population growth are zero, and no technological change occurs. The government finances its purchases by a proportional tax on output at the rate \tau:

G = \tau Y,

where \tau is constant over time.

a. What is the growth rate of Y? Does the model exhibit a convergence property? Why or why not?

b. How does the growth rate depend on \tau? What condition holds if \tau is chosen to maximize the growth rate?

c. Are the outcomes Pareto optimal if \tau is set to maximize the growth rate? How does this result relate to the usual view that lump-sum taxation is superior to proportional taxation?

PART II:
Answer BOTH questions:

2.—

a.) Under what assumptions does the permanent income hypothesis predict that consumption should follow a random walk?

b.) Derive explicitly the random walk of result (a).

c.) Discuss briefly what you know about the empirical evidence on the random walk.

d.) Consider a pre-announced future temporary tax cut. What are the effects on consumption of this policy before, during, and after the tax cut? Consider the cases of: (1) the life cycle model; (2) the life cycle model with bequests, (3) the Keynesian consumption function; (4) a life cycle model with liquidity constraints.

3. Consider a monopolistic trade union, that can unilaterally set the nominal wage. The union’s utility function is:

\displaystyle U = \left(\frac{w}{p}\right)^{\frac{1}{2}} + \beta N

Where: w is the nominal wage
p is the price level
N is employment
and \beta>0 is a parameter.

\displaystyle N = n_0 - \alpha\frac{w}{p},

where n_0>0 and \alpha>0 are parameters

1) Suppose first that p is fixed, and compute what is the nominal wage chosen by the union.

2) Suppose that a monetary authority can influence the price level with monetary policy, and suppose that the union can change the nominal wage at any time but with a small cost; that is, any change in the nominal wage has a very small administrative cost for the union. Discuss the effects of monetary policy in this model.

PART III:
Answer ONE of the following two questions:

4. Consider the case of a central bank conducting monetary policy in a standard fractional reserve banking system. The central bank can set either the short-term interest rate or the quantity of bank reserves (but not both simultaneously) to whatever level is chosen. What factors determine the central bank’s optimal choice of which one to set, under each of the following sets of circumstances?

(a) The central bank is trying to come as close as possible to hitting a target for the money stock (defined as public holdings of bank deposits).

(b) The central bank is trying to come as close as possible to hitting a target for real output.

In answering each part, show explicitly what difference (if any) it makes whether the economy is subject to aggregate supply shocks or whether demand-type disturbances are the only ones the economy faces.

5. Under what conditions can a central bank’s prior announcements of its policy actions influence the macroeconomic effect of those actions? If the central bank is free to conduct a politically independent monetary policy, what determines whether it will then actually implement the actions it has announced? Be explicit about the assumptions on which your answer relies.

PART IV:
Answer TWO of the following THREE questions:

6. Consider an unemployed worker searching for work. Each period she draws a wage offer w from a distribution F(w). Assume that there are no quits or layoffs so once the worker accepts a job, she works at it forever. Assume that wages in future periods are discounted by \beta.

(a) Write a Bellman equation that characterizes the value of an optimal search policy given a current offer of w.

(b) The optimal policy is to set a reservation wage. Explain what this means and write an equation that implicitly defines the reservation wage.

(c) Suppose that the worker only receives a wage offer with probability \phi each period. Explain in words or equations what happens to the reservation wage and why?

(d) Suppose that the worker receives two wage offers each period. Explain in words or equations what happens to the reservation wage and why?

7. Consider the following open economy macroeconomic model

(1) Y = f(K, L)
(2) W/P = f_L
(3) Y = C(Y) + G + NX(e, Y)
(4) e = EP^*/P
(5) M/P = L(Y)

Where asterisks denote foreign variables, NX is net exports, E is the nominal exchange rate and all other variables have their usual interpretations.

(a) What is the sign of \partial NX/\partial e? Explain.

(b) Suppose that workers and firms set nominal wage contracts:

W = \bar{W}

What is the effect of a change in M or in G on Y?

(c) Suppose that wages are indexed to the CPI:

W = \bar{w}P^{\alpha}(EP^*)^{1-\alpha}

What is the effect of a change in M or in G on Y?

8. Suppose that price in a market is initially equal to zero, but is expected to rise linearly with time:

p(t) = \alpha t.

Suppose that you have a machine that costs k to install and once installed produces a unit flow of output. Time is continuous and the date zero present value of a dollar at date t is e^{-rt}.

(a) At what date t should you have the machine installed in order to maximize profits?

(b) What is the present value of profits at the optimal time of investment?

(c) What is the value of Tobin’s Q at the optimal time of investment? What did Tobin argue should be the relationship between Q and investment? Speculate about what is special about the case considered here.

Source: Department of Economics, Harvard University. Past General Exams, Spring 1991-Spring 1999, pp. 84-88. Private copy of Abigail Waggoner Wozniak.

Image Source: Harvard University Economics PhD graduates from May 2025.

Categories
Exam Questions Harvard Macroeconomics

Harvard. General Exam in Macroeconomic Theory. Spring 1993


The following general examination for macroeconomic theory (Spring 1993) has been transcribed from a collection of general exams at Harvard from the 1990s provided to Economics in the Rear-view Mirror by Abigail Waggoner Wozniak (Harvard economics Ph.D., 2005). Abigail Wozniak was an associate professor of economics at Notre Dame before being appointed a senior research economist and the first director of the Federal Reserve Bank of Minneapolis’ Opportunity & Inclusive Growth Institute.

Economics in the Rear-view Mirror is most grateful for her generosity in sharing this valuable material.

Because the “Wozniak collection” is over 90 pages long, it will take some time for all the exams to get transcribed. To date the following transcriptions are available for:

Spring 1991

Microeconomics; Macroeconomics

Spring 1992

Micro- and Macroeconomics

Fall 1992

Micro- and Macroeconomics

Spring 1993

Microeconomics

_______________________________

HARVARD UNIVERSITY
DEPARTMENT OF ECONOMICS

Economics 2010d: Final Examination
and
GENERAL EXAMINATION IN MACROECONOMIC THEORY

Spring Term, 1993

For those taking the GENERAL EXAM in macroeconomic theory:

  1. You have FOUR hours.
  2. Answer a total of SIX questions subject to the following constraints:

— answer both questions from Part I;
— answer two questions from Part II;
— answer two questions from Part III.

For those taking the FINAL EXAMINATION in ECONOMICS 2010d (not the General Examination):

  1. You have THREE hours.
  2. Answer a total of four questions subject to the following constraints:

— DO NOT ANSWER ANY questions from Part I;
— answer two questions from Part II;
— answer two questions from Part III.

PLEASE USE A SEPARATE BLUE BOOK FOR EACH QUESTION, AND WRITE THE QUESTION NUMBER ON THE FRONT OF THE APPROPRIATE BLUE BOOK.

PLEASE PUT YOUR EXAM NUMBER ON EACH BOOK.

PLEASE DO NOT WRITE YOUR NAME ON YOUR BLUE BOOKS.

*  *  *  *  *  *  *  *  *  *  *  *  *  *

Part I. (Answer both questions)

Question 1:

Consider the following dynamic, perfect-foresight version of the IS-LM model:

R=R-\dot{R} /\rho

r=\alpha y-\beta m

\dot{y} =\gamma \left( d-y \right)

d=\lambda y-\theta R+g

where

R is the long-term interest rate,
r is the short-term interest rate,
y is output,
m is (exogenous) real money balances,
d is demand,
g is a measure of (exogenous) fiscal policy,
and all parameters are positive and 0<\lambda <1.

    1. Give an interpretation of each equation.
      (Hint: When long-term interest rates rise, bond prices fall.)
    2. Write the model using two variables and two laws of motion. Identify the state (non-jumping) variable and the costate (jumping) variable.
    3. Draw the phase diagram, including the steady-state conditions, the implied dynamics, and the saddle-point stable path.
    4. Describe the effects of an immediate permanent decrease in g. What happens to short-term and long-term interest rates?
    5. Describe the effects an announced future permanent decrease in g. (This scenario is also known as the Clinton plan). What happens to short-term and long-term interest rates?

Question 2:

Endogenous Money

Monetary aggregates, such as the monetary base and broader concepts like M1 or M2, appear to be procyclical. It is sometimes argued that this pattern can be explained from models of “endogenous money,” that is, frameworks in which money moves in response to changes in the economy.

  1. Suppose that the monetary authority varies the money supply in order to maintain a desired path of the price level, for example, to maintain price stability. Can this monetary rule create a procyclical pattern for money even if money has no effect on real variables? What happens if the monetary authority targets a nominal interest rate instead of, or in addition to, the price level?
  2. Suppose that the monetary authority wants to peg an exchange rate, rather than the domestic price level. Would the targeting of an exchange rate create a procyclical pattern for money?
  3. Does the idea of endogenous money imply that broad aggregates like M1 or M2 will be more procyclical than a narrow aggregate like the monetary base?
  4. Can the idea of endogenous money explain why money and output move together on a seasonal basis (using seasonally-unadjusted data!)?
PART II

Answer any two of the following three questions. Be sure to use a separate bluebook for each answer.

  1. “It’s absurd to think that monetary policy actions, as conventionally implemented by central banks in advanced industrialized economies, have any more than a trivial impact on either real economic magnitudes or prices. For example, in the United States an enormous financial market holds and trades approximately $4 trillion of government securities and more than that amount of debt securities issued by other borrowers, yet supposedly the difference between a highly “expansionary” monetary policy and a highly “restrictive” monetary policy amounts to whether the central bank buys $10 billion more or less of government securities over the course of an entire year. Hah! Open market operations in such trivial amounts (compared to the size of the economy and the financial markets) can’t have much impact on anything. Further, since the majority of U.S. bank liabilities are not subject to reserve requirements, the idea that these open market operations affect the economy by regulating the banking system’s ability to create money and/or extend credit doesn’t make sense either.”
    Construct the strongest argument you can to disagree with this statement.
  2. The U.S. Treasury has just announced its intention to change the maturity structure of its outstanding debt by issuing fewer long- and medium-term securities and more short-term securities. The stated rationale for this change is to save on the government’s interest payments. (Long-term Treasury bonds currently yield around 7%, short-term bills around 3%, and medium-term notes somewhere in between depending upon the maturity.)
    1. Under what assumptions would this kind of debt management action actually deliver reduced interest costs over the long run?
    2. Under what assumptions would this kind of debt management action not deliver reduced interest costs over the long run?
    3. Under what assumptions would this kind of debt management action not deliver reduced interest costs over the long run, but reduce the government’s budget deficit over the long run anyway?
  3. —
    1. Evidence drawn from the experience of OECD countries over the last three decades strongly suggests that disinflations (that is, reductions in the rate of increase of prices) are typically costly, in the sense of involving foregone real output compared to what a disinflating economy would otherwise have produced if its inflation rate had remained unchanged. What features of economic behavior account for this foregone output? In answering, be specific about how the elements to which you point affect real output. Also indicate whether your answer implies that disinflations brought about by restrictive monetary policy are likely to be more or less costly (again, in the sense of foregone output) than disinflations that occur for other reasons.
    2. In light of your answer to (a), why do you think there is not more discussion of the “gain” associated with increasing inflation rates, to parallel the usual discussion of the “sacrifice” associated with disinflation?
Part III. (Answer two questions)

Answer any two of the following three questions.

Question 6

    1. Consider a small open economy characterized by the following equations

Y\  =\  C\left( Y \right) +I\left( r^{\ast} \right) +G+X\left( e \right) -eM\left( e \right)

M/P\ =\ L\left( Y,r^{\ast} \right)

where all variables have their standard meaning, e is the real exchange rate, e = EP*/P and * denotes a foreign variable. Assuming that the price level is fixed, what is the effect of an increase in G on output and net exports under fixed and flexible exchange rates? What assumptions on X and M do you need to make in the flexible rate case?

    1. Now consider another small open economy with a representative agent that chooses consumption to maximize the present discounted value of consumption

\max_{\left\{ c_{t} \right\}} \int_{0}^{\infty} e^{-\alpha t}\  ln\  c\  dt

where c denotes consumption, α the discount rate, and t indexes time. The agent receives a constant flow income of \bar{y} and can borrow and lend at the world interest rate which is also α. What is the economy’s current account? Suppose that at time 0 the government decides to erect a monument to its own greatness. The monument will cost γ in time 0 income. What is the effect on the current account if the government finances construction by confiscating αγ from \bar{y} at each instant? What is the effect on the current account if the government issues bonds to finance construction and postpones the implementation of the income tax until time t=\Gamma >0?

(c) Speculate as to why the effect on the current account in the flexible rate part of (a) differs from the bond financing part of (b)?

Question 7

Suppose that the exchange rate (x) depends on some fundamentals (f) and the expected rate of appreciation or depreciation as follows:

x\left( f_{t} \right) =f_{t}+\frac{1}{dt} E_{t}dx\left( f_{t} \right).

Suppose further that fundamentals follow a Brownian motion without drift

df=\sigma dw

where w is a Wiener process.

    1. Use Ito’s lemma to write a differential equation for x and solve it. [Hint: the solution should contain three terms, two of which should involve exponentials and the third should be f].
    2. Suppose that initially f < \bar{f} and that each time the fundamentals reach the level \bar{f} , the government follows a policy of resetting the fundamentals to \bar{f} -  c < \bar{f}. What boundary conditions allow you to solve for x(f). (Hint: consider what happens when the government intervenes and when f approaches -∞.)
    3. Graph the solution for x(f) from (b). What effect does the policy of intervention at \bar{f} have on the variance of x? Is var(x) < var(f)?
    4. What does your answer in part (c) lead you to conclude about the desirability of exchange rate systems such as the European Monetary System in which the currency government maintains the currency between two bands?

Question 8

Consider a firm with the following loss function

\Pi \left( p_{i},p,m \right) =-\gamma \left( p_{i}-p-\alpha \left( m-p \right) \right)^{2}

where pi is the firm’s nominal price, p is a price index, m is the money supply, and \gamma is a positive constant. All variables are in logs. Suppose that initially

pi = p = m = 0.

    1. Suppose that the firm incurs a fixed cost β each time it alters its nominal price. Characterize the optimal policy in the face of a once and for all change in m given that the price index remains constant and that the firm discounts future losses at the rate r. How does this policy depend on the curvature of the loss function (γ) and the discount rate (r)?
    2. Suppose that the economy is made up of many firms just like the one above and that the log price index is just the average of their log prices

\left( p=\int p_{i}di \right).

What policy would these firms follow in the face of a once and for all change in the money supply if they could agree to follow identical strategies? How does your answer differ from part (a). Interpret the role of α.

    1. How would you expect your answer to part (a) to change if instead of a one time change, the money supply followed a process with variance σ.

Source: Department of Economics, Harvard University. Past General Exams Spring 1991-Spring 1999, pp. 53-59. Copy provided to Economics in the Rear-view Mirror by Abigail Wozniak.

Categories
Exam Questions Harvard

Harvard. General Examination in Microeconomic Theory. Spring, 1993

Economics in the Rear-view Mirror has been provided a copy of nearly all the 1990s general exams in micro- and macroeconomic theory from Harvard through the collegial generosity of Minneapolis Fed economist Abigail Wozniak. With this post you now have the Spring 1993 graduate general exams in microeconomic theory.

While these exams lie outside of my personal comfort zone as a historian of economics (1870-1970), for fledgling historians of economics of today and tomorrow these are indeed legitimate historical artifacts definitely worth transcription. I am rather slow in digitizing them because transcription of mathematics for this blog requires latex inserts. Latex expressions involve considerably longer roundabout production than the application of my talents for touch-typing/OCR to non-mathematical text. Patience! The Rest is Yet to Come! 

________________________________

Previously Transcribed Harvard Graduate General Exams

Spring 1989: Economic Theory

Spring 1991: Microeconomics; Macroeconomics

Spring 1992: Micro- and Macroeconomics

Fall 1992:  Micro- and Macroeconomics

________________________________

Graduate Microeconomic Theory Sequence, 1992-93

Economics 2010a. Economic Theory

Michael D. Whinston and Eric S. Maskin

Covers the theory of individual behavior including the following topics: constrained maximization, duality, theory of the consumer, theory of the producer, behavior under uncertainty, consumer choice of financial assets, externalities, monopolistic distortions, game theory, oligopolistic behavior, asymmetric information.

Prerequisite: Economics 2030 or equivalent; can be taken concurrently.
Half course (fall term). Tu., Th., 10-11:30.

Economics 2010b. Economic Theory

Andreu Mas-Colell and Stephen A. Marglin

General equilibrium, stability, pure and applied welfare economics, uncertainty, descriptive and optimal growth theory, income distribution, methodology.

Prerequisite: Economics 2010a.
Half course (spring term). Tu., Th., 10-11:30.

Source: Harvard University, Faculty of Arts and Sciences. Courses of Instruction 1992-1993, p. 248.

________________________________

HARVARD UNIVERSITY
DEPARTMENT OF ECONOMICS

Economics 2010b: FINAL EXAMINATION and
GENERAL EXAMINATION IN MICROECONOMIC THEORY

Spring Term 1993

For those taking the GENERAL EXAM in microeconomic theory:

  1. You have FOUR hours.
  2. Answer a total FIVE questions subject to the following constraints:

— at least ONE from Part I;
— at least TWO from Part II;
— EXACTLY ONE from Part III.

For those taking the FINAL EXAMINATION in Economics 2010b (not the General Examination):

  1. You have THREE HOURS
  2. Answer a total of four questions subject to the following constraints:

— DO NOT ANSWER ANY questions from Part I;
— at least TWO from Part II;
— at least ONE from Part III.

PLEASE USE A SEPARATE BLUE BOOK FOR EACH QUESTION

PLEASE PUT YOUR EXAM NUMBER ON EACH BOOK

Part I (Questions 1 and 2)

  1. Suppose that there are J firms producing good \ell differentiable cost function c(w,q) where w is a vector of input prices and q is the firm’s output level. The differentiable aggregate demand function for good \ell is x(p), where p is good \ell’s price. Assume c(w,q) is strictly convex in q and that x´(p)≤0. Also assume that partial equilibrium analysis is justified.
    1. Suppose that all factor inputs can be adjusted in the long-run, but that input k cannot be adjusted in the short-run. Suppose that we are initially at an equilibrium where all inputs are optimally adjusted to the equilibrium level of output \bar{q} and factor prices \bar{w} so that, letting z_{k}\left( \bar{w} ,\bar{q} \right) be the conditional factor demand function for factor k, we have z_{k}=z_{k}\left( \bar{w} ,\bar{q} \right). What can be said about the short-run versus long-run output response of the firm to a differential change in the price of good \ell? What does this imply about the short-run versus long-run equilibrium response of p to a differential exogeneous shift in the demand function (hold the number of firms fixed in both cases)? (Hint: Define a short-run cost function c_{s}\left( w,q,z_{k}\right)  giving the minimized cost of producing output q given factor prices w when factor k is fixed at level z_{k}).
    2. Now suppose that all factor inputs can be freely adjusted. Give the weakest possible sufficient condition, stated in terms of marginal and average costs and/or their derivatives, that guarantees that if the price of input k\left( w_{k}\right) marginally increases, then firms’ equilibrium profits decline for any demand function x\left( \cdot \right) with x^{\prime }\left( \cdot \right)  \leq 0. Show that if your condition is not satisfied, then there exist demand functions such that profits increase when the price of input k increases. What does your condition imply about the firm’s conditional factor demand for input k?
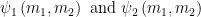
  2. A. Consider a one-shot two-player game in which player 1 has a set of possible moves M1 (with n1 elements) and player 2 has a set of possible moves M2 (with n2 elements). Players move simultaneously. How many strategies does each player have?

B. Now suppose that the game is changed so that player 1 moves before 2, and 2 observes 1’s move, but that the game is otherwise the same as before. That is, the sets of moves are still M1 and M2, and player 1’s and 2’s payoffs as functions of moves \psi_{1} \left( m_{1},m_{2}\right) \text{ and } \psi_{2} \left( m_{1},m_{2}\right), respectively, are unchanged. How many strategies does each player have in the altered game?
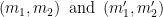
C. The game of part B may have multiple subgame-perfect equilibria. Show, however, that, if this is the case, there exist two pairs of moves \left( m_{1},m_{2}\right)\text{ and } \left( m^{\prime }_{1},m^{\prime }_{2}\right) (where either m_{1}\neq m^{\prime }_{1}\text{ or } m_{2}\neq m^{\prime }_{2} ) such that either

(*) \psi_{1} \left( m_{1},m_{2}\right)  =\psi_{1} \left( m^{\prime }_{1},m^{\prime }_{2}\right)
or
(**) \psi_{2} \left( m_{1},m_{2}\right)  =\psi_{2} \left( m^{\prime }_{1},m^{\prime }_{2}\right).

D. Suppose that, for any two pairs of moves \left( m_{1},m_{2}\right)\text{ and } \left( m^{\prime }_{1},m^{\prime }_{2}\right)  such that m_{1}\neq m^{\prime }_{1}\text{ or } m_{2}\neq m^{\prime }_{2}, (**) is violated, i.e., \psi_{2} \left( m_{1},m_{2}\right)  \neq \psi_{2} \left( m^{\prime }_{1},m^{\prime }_{2}\right). In other words, player 2 is never indifferent between pairs of moves. Suppose that there exists a pure-strategy equilibrium in the game of part A in which \pi_{1} is player 1’s payoff. Show that in any subgame-perfect equilibrium of part B, player 1’s payoff is at least \pi_{1}. Would this conclusion necessarily hold for any Nash equilibrium of part B? Why or why not?
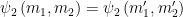
E. Show, by example, that the conclusion of part D may fail if either

(a) \psi_{2} \left( m_{1},m_{2}\right)  =\psi_{2} \left( m^{\prime }_{1},m^{\prime }_{2}\right)  holds for some pair \left( m_{1},m_{2}\right)  ,\left( m^{\prime }_{1},m^{\prime }_{2}\right) with m_{1}=m^{\prime }_{1}\text{ and } m_{2}=m^{\prime }_{2}; or

(b) we replace the phrase “pure-strategy equilibrium” with “mixed-strategy equilibrium.”

Part II (Questions 3, 4, & 5)

QUESTION 3 (General Equilibrium with Gorman Preferences)
(20 points)

Suppose you have a population of consumers i = 1,….,I. Ever consumer i has an endowment vector of commodities \omega_{i} \in R^{I} and preferences expressed by an indirect utility function v_{i}\left( p,w_{i}\right).

(a) (5 points)

Let \left(\bar{x}_{1},\cdots,\bar{x}_{I}\right) be a Pareto optimal allocation. The utility levels of this allocation are \left(\bar{u}_{1},\cdots,\bar{u}_{I}\right). The second welfare theorem asserts the existence of a price vector \bar{p} and wealth levels \left(\bar{w}_{1},\cdots,\bar{w}_{I}\right) supporting the allocation. What does this mean? Express \left(\bar{u}_{1},\cdots,\bar{u}_{I}\right) in terms of the indirect utility functions.
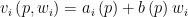
Assume for the next two parts of this question (b and c) that the indirect utility functions take the (Gorman) form v_{i}\left( p,w_{i}\right)  =a_{i}\left( p\right)  +b\left( p\right)  w_{i}. Note that b\left(\cdot\right) does not depend on i. In the following, neglect always boundary allocations. Use of pictures is permissible and helpful.
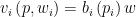
(b) (5 points)

Show that for the above family of utility functions all the Pareto optimal allocations are supported by the same price vector.

(c) (5 points)

Use the conclusion of part (b) to argue that the Walrasian equilibrium allocation is unique. (Assume preferences are strictly convex.)

For the last part of the question (d) assume that indirect utilities are of the form v_{i}\left( p,w_{i}\right)=b_{i}\left(p_{i}\right)w, that is, the preferences on commodity bundles are homothetic (but possibly different across consumers).

(d) (5 points)

Argue by means of an Edgeworth box example (or in any other way you wish!) that the multiplicity of Walrasian equilibria is possible even if preferences are restricted to be homothetic.

QUESTION 4 (Revelation of Information Through Prices)
(20 Points)

Suppose there are two equally likely states s_{1},s_{2} and two traders. In each state there is a spot market where a good is exchanged against numeraire. The utilities of the two traders are (the second good is the numeraire):

STATE 1 STATE 2
TRADER 1 2 ln x11 – x21

4 ln x11 + x21

TRADER 2

4 ln x12 – x22

2 ln x12 + x22

The total endowment of the first good equals 6 in the first state and 6+\varepsilon    in the second state. All the endowments of this good are received by the second trader. Assume that the endowments of numeraire for the two traders are sufficient for us to neglect the possibility of boundary equilibria. The price of the numeraire is fixed to 1 in the two states. The prices of the non-numeraire good in the two states are denoted \left( p_{1},p_{2}\right)  .

(a) (5 points)

Suppose that when uncertainty is resolved both traders know which state of the world has occurred. Determine the spot equilibrium prices \left(\hat{p}_{1}\left(\varepsilon\right) ,\hat{p}_{2}\left(\varepsilon\right)  \right) in the two states (as function of the parameter \varepsilon).

(b) (5 points)

We assume now when a state occurs Trader 2 knows it while Trader 1 remains uninformed (i.e. s/he must keep thinking of the two states or equally likely). Under this information set up determine the spot equilibrium prices \left( \bar{p}_{1}\left(\varepsilon\right) ,\bar{p}_{2}\left(\varepsilon \right)\right) in the two states.

(c) (5 points)

We are as in (b), except that now we allow Trader 1 to deduce the state of the world from prices. That is, if p_{1}\neq p_{2} then Trader 1 is actually informed while if p_{1}=p_{2}, s/he is not informed. A system of equilibrium spot prices \left( p^{\ast }_{1}\left(\varepsilon\right) ,p^{\ast }_{2}\left(\varepsilon\right) \right) is a rational expectation equilibrium if at the equilibrium Trader 1 derives information from \left( p^{\ast }_{1}\left(\varepsilon\right) ,p^{\ast }_{2}\left(\varepsilon\right) \right) in the manner described. Let \varepsilon \neq 0. Exhibit a rational expectations equilibrium. Comment.

(d) (5 points)

Show that if \varepsilon = 0 then there is no rational expectations equilibrium.

QUESTION 5 (20 Points)

There are three participants in a public good decision problem with two outcomes. If the public good project is not carried out then the utility is zero for everybody. If it is carried out then the utility is 3 for the “project-lovers” and -1 for the “project-haters.” The cost of the project is zero.

We consider first the following decision mechanism. People are asked if they are PL (project-lovers) or PH (project haters). If at least one participant announces PL the project is carried out and the self-declared PH are exactly compensated for their loss. The resources for the compensation comes from a tax imposed on the self-declared PL (equal across them).

(a) (5 points)

Show that the above mechanism is not straightforward. Define your terms.

(b) (5 points)

Suppose now that participants know each others characteristics (i.e. if they are project-lovers or project-haters). Consider the situation where everybody self-declares truthfully. Argue that this is an equilibrium (i.e. it does not pay to any participant to deviate) if there is one but not if there are two PLs. Which are the equilibrium situations in the latter case?

We now change the set-up somewhat. Suppose that the designer knows how many PLs there are and that the participants know that the designer knows (or, simply you can assume that both designer and participants have this information). Say that the number of PLs is \alpha \in \left( 1,2,3\right)  . (Hence there is at least one PL.) Then the decision mechanism is as above except that for the project to be carried out it is now required that at least \alpha self-declare as PL.

(c) (5 points)

Show that for this mechanism it does not always pay to self-declare truthfully (that is, the truth is not a dominant strategy).

(d) (5 points)

Suppose that it is understood (Precisely, it is common knowledge) that no participant will ever use a dominated announcement. Show then that it cannot hurt to self-declare truthfully (technically, the truth is dominant after one round of deletion of dominated strategies. There is a subtle point here—that you may want to discuss—namely, if “dominated” should be understood as “weakly dominated” or “strongly dominated.” The distinction does not matter for the case \alpha =1 but it does for the case \alpha =2.)

Part III (Questions 6 and 7)

  1. (a) How does the following idea (or vision, in Schumpeter’s sense of the term) get reflected in the neo-Keynesian model presented in this course?

…there is a subtle reason drawn from economic analysis why…faith may work. For if we act consistently on the optimistic premise, this hypothesis will tend to be realized; whilst by acting on the pessimistic premise, we keep ourselves for ever in the pit of want. (Keynes, Essays in Persuasion, pp. vii-viii)

(b) Why does Knight’s dictum [following] fail to characterize the neo-Keynesian model?

…competition among even a very few [entrepreneurs]will raise the rate of contractual returns [wages] and lower the residual share [profits], if they know their own powers. If they do not, the size of their profits will again depend on their “optimism,” varying inversely with the latter. (Knight, Risk, Uncertainty, and Profit, p. 285.)

(c) Is it true, as Joan Robinson once wrote, that in a neo-Keynesian conception of the world businessmen are free to make the rate of profit anything they wish?

(d) More generally, how can investment demand be exogenous in a model where income and expenditure must be equal as a condition of equilibrium? What features of the theory allow investors’ preferences and investment demand to play a role in neo-Keynesian theory which differs from the role played by consumers preferences and consumption demand in neoclassical theory?

  1. Economic theories are, among other things, theories of knowledge—implicitly if not explicitly. What is the neoclassical theory of knowledge? Which do you regard as the more serious of the many objections to this theory of knowledge? Why in your view has the theory been able to survive the objections?

Source: Department of Economics, Harvard University. Past General Exams, Spring 1991-Spring 1999, pp. 84-88. Private copy of Abigail Waggoner Wozniak.


Categories
Exam Questions Harvard

Harvard. General Exams in Microeconomic and Macroeconomic Theory. Spring, 1992


The following general examinations for microeconomic and macroeconomic theory (Spring 1992) have been transcribed from a collection of general exams at Harvard from the 1990s provided to Economics in the Rear-view Mirror by Abigail Waggoner Wozniak (Harvard economics Ph.D., 2005). Abigail Wozniak was an associate professor of economics at Notre Dame before being appointed a senior research economist and the first director of the Federal Reserve Bank of Minneapolis’ Opportunity & Inclusive Growth Institute. Economics in the Rear-view Mirror is most grateful for her generosity in sharing this valuable material.

The “Wozniak collection” is over 90 pages long, so it will take some time for all the exams to get transcribed.

Transcriptions are also available for: 

Spring 1991. General Examinations in Microeconomic Theory and Macroeconomic Theory.

Fall 1992. Microeconomic Theory and Macroeconomic Theory.

___________________________

HARVARD UNIVERSITY
DEPARTMENT OF ECONOMICS

Economics 2010b: FINAL EXAMINATION and
GENERAL EXAMINATION IN MICROECONOMIC THEORY

Spring Term 1992

For those taking the GENERAL EXAM in microeconomic theory:

  1. You have FOUR
  2. Answer a total of FIVE questions subject to the following constraints:
    *at least ONE from part I;
    *at least TWO from Part II;
    *EXACTLY ONE from Part III.

For those taking the FINAL EXAMINATION in Economics 2010b (not the General Examination):

  1. You have THREE HOURS
  2. Answer a total of four questions subject to the following constraint:
    *DO NOT ANSWER ANY questions from Part I;
    *at least TWO from Part II;
    *at least ONE from Part III.


PLEASE USE A SEPARATE BLUE BOOK FOR EACH QUESTION

PLEASE PUT YOUR NAME (OR EXAM NUMBER) ON EACH BOOK


PART I (Questions 1 and 2)

QUESTION 1

A consumer in a three good economy (goods denoted x1, x2 and x3; prices by p1, p2, p3) with wealth level w>0 has demand functions for commodities 1 and 2 given by:

\begin{array}{l}{{x}_{1}}=100-5\,\,\frac{{{p}_{1}}}{{{p}_{3}}}+\beta \,\,\frac{{{p}_{2}}}{{{p}_{3}}}+\delta \,\,\frac{w}{{{p}_{3}}}\\{{x}_{2}}=\alpha -\beta \,\,\frac{{{p}_{1}}}{{{p}_{3}}}+\gamma \,\,\frac{{{p}_{2}}}{{{p}_{3}}}+\delta \,\,\frac{w}{{{p}_{3}}}\end{array}

Where Greek letters are non-zero constants.

i) Indicate (but don’t actually do it!) how to calculate the demand for the third good, good 3.

ii) Are the demand functions for x1 and x2 appropriately homogeneous?

iii) Calculate the numerical values of \alpha ,  \beta , \gamma . (Hint: what are the various restrictions on the consumer’s demand function and on the relationships between various demand functions? Have you made use yet of all of them?)

iv) Given your results above, draw for a fixed level of x3, the consumer’s indifference curve in the x, y plane.

v) What does your answer to (iv) imply about the form of the consumer’s utility function u(x1, x2, x3)?


QUESTION 2

Consider a Cournot duopoly. The inverse demand function is

p=100 – (q1 +q2)

where qi, i= 1,2, is the production of firm i (Note: if q1+q2 ≥100 then the price is zero). Marginal cost for the two firms is constant and equal to zero.

  1. Show that given the production qi≤100 of firm i the optimal reaction of firm j (j \ne i) is qj = ½ (100-qi). Use this to compute the Cournot-Nash equilibrium. Draw also the reaction function.
  2. Argue that it can never be a best response for any firm to supply more than x1=50. Argue then that if no firm will ever supply more than 50 then no firm will ever supply less than x2=25.
  3. Continue the above recursion and determine the limit of xt. Interpret in terms of the concept of rationalizability (define terms).


PART II (Questions 3, 4 and 5)

QUESTIONS 3

Consider the following 2 person, 2 commodity general equilibrium model. Individual 1 is risk neutral and has a utility function

u1(x,q) = x + y

Individual 2 is risk averse and has von Neumann-Morgenstern utility function

u2(x,y) = x½ + y.

Individual 1’s endowment of good y is {\bar{Y}}, he has no x. There are three states of nature and the endowment of individual 2 depends on the state. The levels of endowment of x are x1, x2 and x3. He has no y.

  1. Suppose the subjective beliefs are that each state is equally likely. Find a complete-market Arrow-Debreu equilibrium.
  2. Suppose there is a market for the delivery of x and y only uncontingently. Find the equilibrium. Is it efficient?
  3. Suppose that before any trade takes place, all individuals will be told whether or not state 1 will arise. They are not able to distinguish between states 2 and 3 at this stage. Find the equilibrium as it depends on the information disseminated.
  4. Calculate the expected utility attained in the equilibrium of part c), ex ante (i.e. before any announcement is known), using the fact that the probability that the individuals will be told that the state is 1 is 1/3, and that it is not 1 is 2/3. Under what conditions (on x1, x2 and x3) is the information socially valuable. Comment.


QUESTION 4

[This problem concerns a firm which is not explicitly optimizing anything. We just want to study the stability of its profitability and debt-equity structure.]

At each instant of time, the firm employs only a single factor, capital, in an amount K. Gross profits are f(K), concave and increasing in K. It has a certain level of borrowing B on which it owes rB in interest costs; r is fixed. Net profits therefore are

\pi = f(K) – rB

Some of the profit is distributed in the form of dividends, D. The rest of it is held as retained earnings R. Suppose the firm follows the “dividend policy”

\begin{array}{l}R=\alpha \pi \,\,\,\,\,\,\,\,\,\,\,\,\,\,0\le \alpha \le 1\\D=\left( 1-\alpha  \right)\pi \end{array}

The change in firm’s stock capital is equal to the sum of its level of retained earnings R and new borrowing B minus depreciation \delta K (\delta > 0)

\dot{K}=R+\dot{B}-\delta K

Its level of new borrowing responds positively to the excess of current net profits above a target level \pi *, according to

\dot{B}=\beta \left( \pi -\pi * \right)

\beta \ge 0.

In an equilibrium, K, B, \pi , R and D are all constant.

1) Assume we have an equilibrium for fixed parameters \alpha and \beta . For what values is it locally stable?

2) Equity in the firm is, by definition, K – B. Find the steady-state debt-equity ratio, in terms of the parameters and the production function.

Assuming that the equilibrium is stable,

3) What is the effect of a small increase in \pi * on the equilibrium debt-equity ratio?


QUESTION 5

There are n men and n women. Each man has an ordering over the set of women, and each woman has an ordering over the set of men. (indifference is not allowed)

  1. Show that in any Pareto optimal system of pairing men and (i.e. a pairing that cannot be dominated by another system), someone must get his/her first choice.
  2. Consider the following system: Each man proposes to the woman whom he most prefers. Women receiving more than one proposal accept the one they like the best. (Women receiving exactly one proposal accept it.)
    Next, all men whose proposals were rejected, propose to the woman they most prefer from among those who have not yet accepted proposals. The rules for acceptance are as above. This continues until all pairings have been completed.
    Is the result a Pareto optimum?
    Is it in the core of this game, suitably defined? (supply your own definition here).
  3. Show by example how the system could be manipulated by a man who knew the preferences of all other men and who could profess false preferences.


PART III (ANSWER EXACTLY 1 QUESTION) (Questions 6 and 7)

QUESTION 6

What does “competition” mean in the context of neoclassical theory? To what extent are neo-Marxian and neo-Keynesian theories compatible with the neoclassical idea of competitive markets? What alternatives to neoclassical adjustment processes characterize Marxian and Keynesian theories?


QUESTION 7

Paul Samuelson once urged us “(r)emember that in a perfectly competitive market it really doesn’t matter who hires whom; so have labor hire ‘capital’”. (“Wages and Interest: a Modern Dissection of Marxian Economic Models.” American Economic Review, 1957) Does it really not matter who hires whom in neoclassical theory? Is the same true in a Marxian framework? A Keynesian framework?


Source: Department of Economics, Harvard University. Past General Exams Spring 1991-Spring 1999, pp. 60-66. Copy provided to Economics in the Rear-view Mirror by Abigail Wozniak.

___________________________

HARVARD UNIVERSITY
DEPARTMENT OF ECONOMICS

Economics 2010d: FINAL EXAMINATION
and
GENERAL EXAMINATION IN MACRO ECONOMIC THEORY

Spring Term 1992

FINAL EXAMINATION

Instructions for all Economics Department graduate students:

The examination will last four hours.

Answer all three parts of the examination (Parts I, II and III). Within each part, be sure to answer two questions (so that, in all, you will answer six questions).

Use a separate bluebook for each question. Clearly indicate the question number and your identification number on the front of each bluebook.

Do not indicate your name on any bluebook you submit.

Instructions for all other students:

The examination will last three hours.

Answer Parts II and III only. Within each part, be sure to answer two questions (so that, in all, you will answer four questions).

Use a separate bluebook for each question. Clearly indicate the question number and your name on the front of each bluebook.


PART I:

  1.  Consider the following q-theory of investment:

(1) I=I\left( q \right)\,\,\,\,\,\,I\acute{\ }>0

(2) \dot{K}=I-\delta K

(3) r={\left( \dot{q}+\pi  \right)}/{q}\;

(4) \pi =\pi \left( K \right)\,\,\,\,\,\,\,\,\,\pi \acute{\ }

Where I is investment, q is Tobin’s q, K is the capital stock, \delta is the depreciation rate, r is the required rate of return, and \pi is the profit from owning one unit of capital.

  1. What is Tobin’s q?
  2. Interpret each equation.
  3. Write the model in terms of two variables and two laws of motion.
  4. What is the state (non-jumping) variable, and what is the costate (jumping) variable?
  5. Draw the phase diagram for this model, including arrows showing the dynamics, the steady state, and the stable path.
  6. Because of an increase in acid rain, the depreciation of capital (\delta ) suddenly increases. Assume the change is permanent. Compare the old and new steady states.
  7. Describe the transition between the old and the new steady states.
  8. Suppose now that (because of strong environmental policies) the increase in \delta is only temporary. Describe the effects.


Question 2 (Answer both Parts)

  1. (20 minutes)
    The Solow model assumes a constant gross saving rate, whereas the neoclassical growth model determines the saving rate through household optimization.

    1. Explain the forces in the neoclassical growth model that make the saving rate rise or fall as an economy develops.
    2. How does this behavior of the saving rate influence the convergence rate—that is, the per capita growth rate of a poor country relative to a rich country? (Assume here that all countries are closed and have the same underlying parameters of technology and preferences.)
  2. (20 minutes)
    “The imperfection of private credit markets implies that a cut in lump-sum taxes, financed by a budget deficit, affects the economy. In particular, in a full-employment setting,

    1. a larger deficit crowds out private investment, and
    2. a budget deficit is a “bad idea.”
      Discuss and comment.


PART II

Answer any two of the following three questions. Be sure to use a separate bluebook for each answer.

  1. A familiar suggestion to central banks is to conduct monetary policy by “targeting” nominal income. Distinguish (a) the argument for targeting nominal income on the ground that this is the measure of economic activity the central bank should ultimately care about affecting, from (b) the argument for targeting nominal income on the ground that doing so will best enable the central bank to affect some other aspect(s) of economic activity in an optimal way. In your analysis of argument (a), be specific about the preference that this notion of nominal income targeting implies with respect to real income and prices separately, and say whether you think these preferences are sensible (and why). In your analysis of (b), this way would lead to a better outcome than focusing monetary policy directly on those aspects of economic activity that the central bank ultimately seeks to affect.
  2. “When money, interest-bearing government debt and productive capital are imperfect substitutes in investors’ portfolios, the economy can achieve a stable growth equilibrium only if the part of the government’s primary deficit (that is, its deficit exclusive of interest payments) that it finances by issuing new debt is equal to some particular value in relation to the economy’s size, where the deficit/income ratio is uniquely determined by specific parameters describing economic behavior. If the government attempts to run a larger debt-financed primary deficit, its growing debt will crowd out private capital, which in turn will raise the real interest rate, which will cause the government’s interest payments to rise, which will make its outstanding debt grow even faster—all in an explosive way—and vice versa if the deficit/income ratio is too small.” Do you agree or disagree with this statement? Why? Be specific about the assumptions underlying your answer.
  3. Under what conditions would the government’s choice among alternative forms of interest-bearing debt, to finance a given non-monetized deficit, affect (a) the aggregate level of real economic activity, and/or (b) the composition of real economic activity, and/or (c) the price level? Why? Under what conditions would this choice affect none of (a), (b) or (c)? Be explicit about the assumptions you make in describing both sets of conditions.


PART III

QUESTION 6

Consider an economy with overlapping generations of identical two-period lived consumers who work in the first period of their life and consume in the second period. The utility function of a consumer representative of the generation born at time t is

{{U}_{t}}={{c}_{t+1}}-\frac{1}{2}a_{t}^{2},

Where ct+1 denotes the consumption taking place at t +1, of a consumer born at t and a her labor supply at time t. Output is produced with labor using a linear production function: one unit of labor yields one unit of output. Output is non-storable. Population is constant.

  1. Show that the competitive equilibrium of this economy is Pareto sub-optimal. Explain why.
  2. Propose two schemes to eliminate this inefficiency. Show precisely how to implement them and compare the resulting welfare levels to the welfare level achieved by the economy described in the previous question. [Restrict yourself, for simplicity, to schemes yielding constant consumption and employment over time.]
  3. What is the channel through which your two proposed schemes affect employment? How does this channel compare with the transmission mechanism of i) real business cycle models, and ii) Keynesian models?

QUESTION 7

You are asked to testify in the Senate about the advisability of phasing out the current U.S. social security scheme. Sketch the argument that you would make in favor of or against this phasing out, knowing that the Senators whom you are addressing have no tolerance for mathematics.

QUESTION 8

In a large open economy, what is the equilibrium effect on national saving and investment of a shift in desired domestic saving (originating, say, from a change in how patient domestic consumers are) or in desired domestic investment (coming, for instance, from a permanent productivity shock)? Does your answer shed any light on the debate about how well international capital markets operate?


Source: Department of Economics, Harvard University. Past General Exams Spring 1991-Spring 1999, pp. 67-71. Copy provided to Economics in the Rear-view Mirror by Abigail Wozniak.


Categories
Exam Questions Harvard

Harvard. General Examinations in Micro- and Macroeconomic Theory, Fall 1992


The following general examinations for microeconomic and macroeconomic theory (Fall 1992) have been transcribed from a collection of general exams at Harvard from the 1990s provided to Economics in the Rear-view Mirror by Abigail Waggoner Wozniak (Harvard economics Ph.D., 2005). Abigail Wozniak was an associate professor of economics at Notre Dame before being appointed a senior research economist and the first director of the Federal Reserve Bank of Minneapolis’ Opportunity & Inclusive Growth Institute. Economics in the Rear-view Mirror is most grateful for her generosity in sharing this valuable material.

The “Wozniak collection” is over 90 pages long, so it will take some time for all the exams to get transcribed.

Transcriptions are available for:

Spring 1991 General Examinations in Microeconomic Theory and Macroeconomic Theory.

___________________

HARVARD UNIVERSITY
DEPARTMENT OF ECONOMICS

GENERAL EXAMINATION IN MICROECONOMIC THEORY
FALL 1992

Instructions:

  1. You have FOUR
  2. Answer a total of FOUR questions subject to the following constraint:
    There are four sections (I, II, III, IV). You must answer ONE question from each section.
  3. Please use a separate blue book for each question.
  4. Please put only your EXAM NUMBER on the blue book.


PART I

  1. Suppose that the consumption set is X=\left\{ x\in \mathbb{R}_{+}^{2}:{{x}_{1}}+{{x}_{2}}\ge 1 \right\} and the utility function is u(x) = x2.
    1. Represent graphically the consumption set and the indifference map.
    2. State and show that the locally cheaper consumption test for demand fails at the price/wealth combination (p, w) = (1, 1, 1).
    3. Show that market demand is not continuous at the above price/wealth combination. Interpret economically.
  2. An individual has Bernoulli utility indicator u and initial wealth w. Let lottery L offer a payoff of G with probability q and a payoff of B with probability 1 – q.
    1. If the individual owns the lottery, what is the minimum price s/he would sell it for?
    2. If s/he does not own it. What is the maximum price s/he would be willing to pay for it?
    3. Are buying and selling prices equal? Give an economic interpretation for your answer. Find conditions on the parameters of the problem under which buying and selling prices are equal.
    4. Let G = 10, B = 5, w = 0 and u(x) = x0.5. Compute the buying and selling prices for this lottery and this utility indicator.


PART II

Consider a market with three identical firms. The three firms set quantities as strategies and do so simultaneously. Each firm has marginal cost c, and market price is

p=1-\sum\limits_{i=1}^{3}{{{q}_{i}}}, where qi is firm i’s quantity.

  1. What are the Cournot equilibrium quantities and prices in this model?
  2. Suppose that firms 1 and 2 consider merging to form a single firm, which would have access to the two firms’ technologies. The merged firm, if it forms, would compete as a Cournot duopolist with firm 3. Assuming that the owners of firms 1 and 2 split the merged firm’s profit equally, would they find such a merger advantageous?
  3. Now suppose that firm 1 sets its quantity (as a Stackelberg leader) first and that firms 2 and 3 then follow and set quantities simultaneously. The model is otherwise the same as before. Suppose that firms 1 and 2 contemplate forming a merged firm that would act as a Stackelberg leader vis a vis firm 3. Will the merged firm’s profit be higher or lower than the sum of firm 1’s and 2’s profits in the pre-merger equilibrium? The question should be answered without making any mathematical computations.


PART III

Consider the country of Ec, a country with a small open economy. Ec’s economy produces two outputs, x and y, from two immobile factors, capital (K) and labor (L). The prices of x and y, px and py, are determined on the world market and are not affected by anything that happens in Ec. The aggregate production function in Ec for x is fx(K,L) and that for y is fy(K,L). Both of these functions are homogeneous of degree one in (K,L), continuous, differentiable, and have strictly convex upper contour sets. Let the input price of K  in Ec be r and that for L be w(these are prices in Ec, not world prices).

  1. Display the set of efficient production plans in an Edgeworth Box. Argue that the contract curve must lie either all above, all below, or be coincident with the diagonal in the interior of this box.

Now assume that production of x is more capital intensive than is production of y in the sense that for any given ratio of input prices, r/w, the cost minimizing way to produce any given amount of output involves a strictly larger capital-labor ratio, K/L, in the production of x than in the production of y.

  1. What can you say about the shape of the contract curve now? How do the slopes of the isoquants of the two production processes vary at various points on the contract curve?

Now assume that Ec has a perfectly competitive economy.

  1. Show that there is a unique equilibrium input price ratio r/w.
  2. Prove that if the world price of the capital intensive good (px) rises, then the equilibrium input price ratio, r/w, increases.
  3. Prove that if the endowment of labor in Ec increases, the output of good y increases and output of good x


PART IV

  1. How is it that, even in a world of linear technologies, different theories of growth and distribution lead to different theories of value, i.e., different theories of relative prices? Doesn’t this violate the non-substitution theorem, which shows that, for a given cost of capital, the technology which minimizes costs will be chosen irrespective of demand? Is the existence of different theories of value compatible with the idea that competition eliminates any difference between price and cost of production? How does utility maximization enter into neoclassical and non-neoclassical theories of value?
  2. Overheard in the corridors of Littauer:
    “I took the best road home yesterday.”
    “How do you know that?”
    “If there had been a better one I would have taken it.”
    Analyze the above dialogue from the point of view of both partisans and critics of revealed preference theory.


Source: Department of Economics, Harvard University. Past General Exams Spring 1991-Spring 1999, pp. 72-77. Copy provided to Economics in the Rear-view Mirror by Abigail Wozniak.

___________________

HARVARD UNIVERSITY
DEPARTMENT OF ECONOMICS

GENERAL EXAMINATION IN MACROECONOMIC THEORY
FALL 1992

Instructions:

  1. You have FOUR
  2. Answer a total of SIX questions subject to the following constraint:
    There are four sections (I, II, III, IV). You must answer ONE question from each section.
  3. Please use a separate blue book for each question.
  4. Please put only your EXAM NUMBER on the blue book.


PART I

  1. Answer the question, “Does money affect output?” Support your answer with both theoretical arguments and empirical evidence. Discuss the strengths and weaknesses of this evidence. Finally, include a detailed discussion of one theory that supports your position.
  2. The response among pundits to the recent reduction in German interest rates has been overwhelmingly positive. Evaluate this response in light of the Mundell-Flemming model. How does foreign monetary policy affect domestic output in the model? What other channel might American commentators have in mind. Speculate about the cause of this difference and give an opinion as to who is correct.


PART II

Problem 1

Consider the following dynamic version of the Mundell-Fleming model:

{{\dot{e}}}/{e}\;={{i}^{*}}-i

i=\alpha y-\beta m

\dot{y}=\gamma \left( d-y \right)

d=\lambda y-\theta e+g

where

e is the exchange rate (measured so that an appreciation of the domestic currency is an increase in e),
i* is the (exogenous) world interest rate,
i is the domestic interest rate,
y is output,
m is (exogenous) real money balances,
d is demand,
g is a measure of (exogenous) fiscal policy,
and \alpha >0,\,\,\beta >0,\,\,\gamma >0,\,\,0<\lambda <1,\,\,\theta >0.

  1. Give an interpretation of each equation.
  2. Write the model using two variables and two laws of motion. Identify the state (non-jumping) variable and the costate (jumping) variable.
  3. Draw the phase diagram, including the steady-state conditions, the implied[?] dynamics, and the saddle-point stable path.
  4. Describe the effects of a sudden, permanent increase in g. Compare the results to the standard (static) Mundell-Fleming model.
  5. Describe the effects of a sudden, permanent increase in Compare the results to the standard (static) Mundell-Fleming model.


Problem 2

Suppose that the representative consumer maximizes the following intertemporal utility function:

{{E}_{t}}\sum\limits_{j=0}^{\infty }{{{\left( 1+\rho  \right)}^{j}}U\left( {{C}_{t+j}},{{G}_{t+j}} \right)}

where C is consumption,

G is (exogenous) government spending,

\rho is the subjective rate of discount,
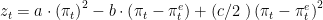
The consumer has random earnings, and she can borrow and lend at the constant real interest rate r.

  1. What is the consumer’s intertemporal first-order condition? Explain.
  2. In this problem, what variable follows a random walk (that is a martingale)? What variable doesn’t? Explain.
  3. Suppose that government spending follows a predictable pattern: in particular, suppose that (for some political reason) G fluctuates as a sine wave. What is the implied pattern of consumption?
  4. Describe the equity-premium puzzle.
  5. Suppose now that government spending is countercyclical (that is, the government increases G when the economy goes into a recession). How might this model help resolve the equity-premium puzzle? What condition would you need for the utility function U(.)?


PART III

  1. What implications for the conduct of monetary policy follow from the fact that many of the familiar variables that economists have urged central banks to adopt as their operating targets—for example, prices, or real interest rates, or measures of money other than the monetary base—are inherently endogenous in the sense that a central bank typically cannot set any of these variables directly via its open market operations? Use a specific model of your choice to illustrate what role a variable like the price level or the real interest rate, or a measure of money other than the monetary base, can plausibly play in the monetary policymaking process even when it is clearly endogenous.
  2. “Whether or not debt-financed government spending ‘crowds out’ private capital formation depends on whether or not the economy’s private resources are already fully employed. At less than full employment, deficit spending will crowd out investment even if it raises output (which it may or may not do). By contrast, the mechanisms that cause this decline in investment at less than full employment are not operative when the economy is fully employed.” Do you agree or disagree with this statement? Explain your reasoning as explicitly as possible.


PART IV

  1. Suppose that the government wishes to minimize the present value of costs, zt, which are given for period t by {{z}_{t}}=a\cdot {{\left( {{\pi }_{t}} \right)}^{2}}-b\cdot \left( {{\pi }_{t}}-\pi _{t}^{e} \right)+\left( {c}/{2}\; \right){{\left( {{\pi }_{t}}-\pi _{t}^{e} \right)}^{2}}
    where a, b, c, > 0 are constants, {{\pi }_{t}} is the inflation rate for period t, and \pi _{t}^{e} is the inflation rate that people expected at the start of period t.

    1. If the government takes \pi _{t}^{e} as given, then what value of {{\pi }_{t}} minimizes the cost zt for period t?
    2. If the government acts as in part I., and everyone knows it, then what is the full equilibrium under conditions of rational expectations? Explain the costs that are borne in this equilibrium. How are they affected by an increase in the parameter a, which measures the cost of inflation? Explain the results.
    3. If the government can commit to an inflation rate for period t, then what rate should it commit to? Explain how the costs in this situation compare with those from the equilibrium in part 2.
    4. Can the equilibrium described under 2. still apply if the government takes account of costs in future periods as well as for period t?
  2. Consider the neoclassical growth model for a closed economy of Solow, Cass, Koopmans, et al.
    1. If we think of all countries as closed, does this model imply convergence in the sense that poor countries tend to grow faster per capita than rich countries? Discuss in your answer the distinction between absolute convergence—where the poor grow faster than the rich—and conditional convergence—where a poor country grows faster for given values of some exogenous variables.
    2. How do the rates of convergence in this model relate in a general way to the diminishing returns to capital and to the behavior of the saving rate? How would the rate of convergence be affected by allowing for some capital mobility across countries?
    3. If poor countries tend to grow faster per capita than rich countries does it follow that the dispersion of per capita incomes across countries will tend to narrow over time?


Source: Department of Economics, Harvard University. Past General Exams Spring 1991-Spring 1999, pp. 78-83. Copy provided to Economics in the Rear-view Mirror by Abigail Wozniak.

Image Source: Harvard Class Album 1946.